
Fuel Tax Refund for Hauliers
This scheme concerns a partial refund of the excise duty on fuel consumed by eligible transport operators. The operations listed in the catalogue are: partial refund of the excise duty on energy products other than natural gas and coal. For taxi operators, an advance on the partial refund of the excise duty paid on energy products bought during 2026 has been introduced. To prepare: reconstruct the volumes actually consumed per vehicle from invoices and fuel records; average estimates do not replace the required supporting documents. The detailed conditions must be checked in the official source before any application or declaration.
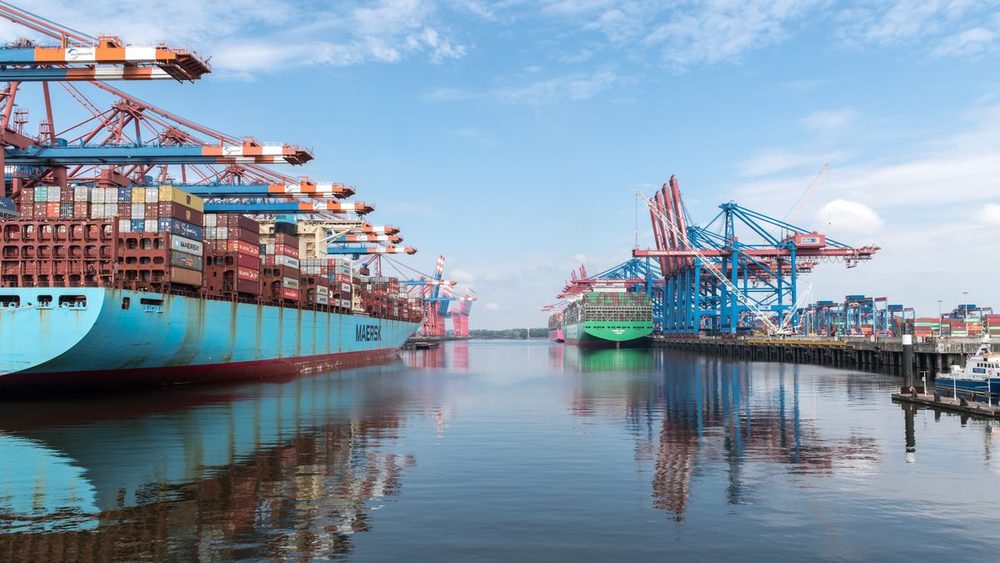
Refund of fuel taxes for transport operators aims to allow, under Articles 265 septies and 265 octies of the French Customs Code, companies using road vehicles to carry goods, public road passenger transport operators and taxi operators to obtain, on request, a partial refund of the excise duty on energy (formerly TICPE) based on their total consumption of diesel and petrol. In practice it covers a partial refund of the excise duty on fuel consumed by eligible transport operators. The key point is to check the beneficiary’s profile, the geographic scope (national aid) and the conditions in force before including the advantage in the company’s budget.
Funded by Ministère de l’Economie, des Finances et de la Souveraineté Industrielle, Energétique et Numérique
Run a personalised scan to identify the public grants and funding your company may be able to access.
Who can apply
Beneficiaries listed in the catalogue: road freight transport companies that own the vehicle, or hold a lease-financing contract or a rental (or sub-rental) contract of 2 years or more, have their registered office in the EU, and use road goods vehicles with a gross weight of 7.5 tonnes or more registered in an EU country; public road passenger transport operators — public- or private-law individuals or legal entities that actually consumed the fuel invoiced to them for a public road passenger transport activity, with their registered office in the EU and operating road passenger vehicles (buses, coaches, rubber-tyred trams, small road trains for tourism and leisure) registered in an EU country; taxi operators. Note: taxi operators who sent, between 1 January 2026 and 31 August 2026, with their VAT return, their excise refund application for quantities bought in 2025 can receive an advance on the refund, paid by bank transfer by 30 September 2026 at the latest. Not eligible for the advance: taxi operators who ceased trading before 1 June 2026; operators who applied for a refund of less than €200 for 2025.
Eligibility conditions
Conditions listed in the catalogue: under decree no. 99-723 of 3 August 1999 as amended, the number of litres of diesel giving entitlement to the refund must be established per vehicle and correspond to the actual successive refuelling during the period. Any method of calculating consumption per vehicle based on an average consumption estimate breaches this obligation and is therefore not admissible. Operators applying for the refund must be able to justify the items declared at any time from the filing of the declaration with the customs office. Invoices and other supporting documents must be presented and kept per vehicle and show that the volume of diesel stated for each vehicle corresponds to its use during the half-year. Diesel purchase invoices must show the place of purchase, the type of fuel, the volume bought and the vehicle’s identification.
What the scheme covers
Operations and exclusions indicated in the catalogue: Partial refund of the excise duty on energy products other than natural gas and coal. For taxi operators, an advance on the partial refund of the excise duty paid on energy products bought during 2026 has been introduced.
Amount and funding terms
Amount and terms indicated in the catalogue: public road passenger transport operators: the refund is calculated, at the company’s choice, either by applying to the volume of diesel used the difference between the floor rate of €39.19 and the rate applicable in the region of purchase, or by applying to the volume of diesel bought in at least 3 regions a flat refund rate weighted by the volumes released for consumption in each region. Road freight carriers: the same choice applies, with a floor rate of €45.19. Depending on the beneficiary’s status, applications can be quarterly, half-yearly or annual. Taxi operators: the refund depends on the operator’s location and the type of fuel, and applications are annual. Advance: 25% of the refund requested in 2026 for products bought in 2025. The advance will be settled — payment of sums still due for purchases in 2026 or, where applicable, repayment of overpayments — during the usual refund campaign from 2027. If the beneficiary does not record the excise amount to be refunded for 2026 during 2027, the advance will be settled by 24 March 2028 at the latest.
How to apply
1. Confirm the eligibility of the activity and the cost period. 2. Gather the invoices, tax notices, proof of payment and required registration documents. 3. Precisely reconstruct the refund basis from the supporting documents. 4. Apply following the official procedure and meet the applicable deadline. 5. Keep the documents used for the calculation.
Timeline
The applicable timetable must be confirmed in the official source. Check the period of costs taken into account, the deadline and any transitional rules.
Key facts
- Funder
- Ministère de l’Economie, des Finances et de la Souveraineté Industrielle, Energétique et Numérique
- Type of funding
- Tax exemption
- Status
- Ongoing
- Geographic scope
- All of France
Frequently asked questions
What is the “Refund of fuel taxes for transport operators” for?
A partial refund of the excise duty on fuel consumed by eligible transport operators.
What advantage is provided?
Amount and terms indicated in the catalogue: public road passenger transport operators: the refund is calculated, at the company’s choice, either by applying to the volume of diesel used the difference between the floor rate of €39.19 and the rate applicable in the region of purchase, or by applying to the volume of diesel bought in at least 3 regions a flat refund rate weighted by the volumes released for consumption in each region. Road freight carriers: the same choice applies, with a floor rate of €45.19. Depending on the beneficiary’s status, applications can be quarterly, half-yearly or annual. Taxi operators: the refund depends on the operator’s location and the type of fuel, and applications are annual. Advance: 25% of the refund requested in 2026 for products bought in 2025. The advance will be settled — payment of sums still due for purchases in 2026 or, where applicable, repayment of overpayments — during the usual refund campaign from 2027. If the beneficiary does not record the excise amount to be refunded for 2026 during 2027, the advance will be settled by 24 March 2028 at the latest.
Who can benefit?
Beneficiaries listed in the catalogue: road freight transport companies that own the vehicle, or hold a lease-financing contract or a rental (or sub-rental) contract of 2 years or more, have their registered office in the EU, and use road goods vehicles with a gross weight of 7.5 tonnes or more registered in an EU country; public road passenger transport operators — public- or private-law individuals or legal entities that actually consumed the fuel invoiced to them for a public road passenger transport activity, with their registered office in the EU and operating road passenger vehicles (buses, coaches, rubber-tyred trams, small road trains for tourism and leisure) registered in an EU country; taxi operators. Note: taxi operators who sent, between 1 January 2026 and 31 August 2026, with their VAT return, their excise refund application for quantities bought in 2025 can receive an advance on the refund, paid by bank transfer by 30 September 2026 at the latest. Not eligible for the advance: taxi operators who ceased trading before 1 June 2026; operators who applied for a refund of less than €200 for 2025.
Which supporting documents should I prepare?
Reconstruct the volumes actually consumed per vehicle from invoices and fuel records; average estimates do not replace the required supporting documents. Consult the official list of documents to enclose.
Official source
No official URL is available in our data for this grant.
Other grants of type “tax exemption”

ACRE: who can benefit from the exemption?
Ministère du Travail et des Solidarités, URSSAF
Innovation tax credit (ITC): rates, expenses and declaration
Ministère de l'Enseignement Supérieur, de la Recherche et de l'Espace, Ministère de l’Economie, des Finances et de la Souveraineté Industrielle, Energétique et Numérique
Up to €400,000
Craft trades tax credit (crédit d’impôt métiers d’art): check eligibility before filing
Ministère de l’Economie, des Finances et de la Souveraineté Industrielle, Energétique et Numérique
Up to €30,000
Other grants from Ministère de l’Economie, des Finances et de la Souveraineté Industrielle, Energétique et Numérique
Aid for works on private property to connect to a fibre-optic network
Ministère de l’Economie, des Finances et de la Souveraineté Industrielle, Energétique et Numérique
Up to €1,200
CODEFI and CIRI: support for companies in difficulty
Ministère de l’Economie, des Finances et de la Souveraineté Industrielle, Energétique et Numérique
Related needs and funding
Competitive calls for projects
Ecological transition and CSR

Capital and investment funds

Support and acceleration

Diagnostics and audits

Takeover and transfer
Discover the funding that fits your company
Check your eligibility for public grants
This scheme is only one of the grants your company may be able to access. Run a personalised scan to identify the funding opportunities that match your activity, location and project.
See the opportunities identified by the scan, then access your personalised report.